Social Security benefits are getting a 3.6% cost-of-living adjustment for 2027. But if you are trying to figure out how much extra money will actually show up in your bank account, multiplying your current deposit by 3.6% may not give you the exact answer.
The Social Security Administration says the increase begins with Social Security benefits paid in January 2027. On average, retirement benefits are expected to rise by about $75 per month.
For your own budget, though, there are two numbers worth separating: your estimated gross Social Security increase and the change in your actual net payment after deductions.
How Much Is the 2027 Social Security COLA?
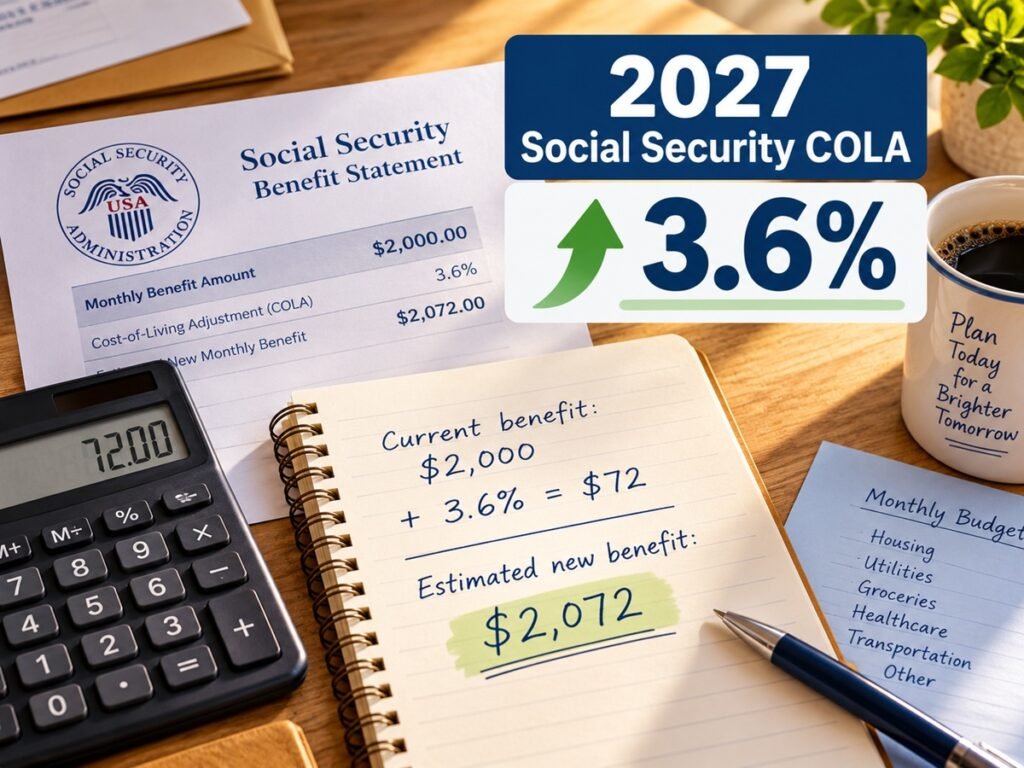
The official 2027 Social Security COLA is 3.6%.
SSA determines the annual adjustment using changes in the Consumer Price Index for Urban Wage Earners and Clerical Workers, commonly called the CPI-W. For the 2027 adjustment, the average CPI-W for the third quarter of 2026 was 3.6% higher than the applicable third-quarter 2025 average.
Nearly 72 million Social Security beneficiaries will receive the increase beginning with payments made in January 2027.
If you receive Supplemental Security Income, or SSI, the higher payment takes effect sooner: the January 2027 SSI payment is scheduled for December 31, 2026 because January 1 is a federal holiday.
How to Estimate Your 2027 Social Security Increase
For a quick estimate, take your current gross monthly Social Security benefit before deductions and multiply it by 0.036.
Estimated monthly increase = current gross benefit × 0.036
Then add that amount to your current benefit:
Estimated new gross benefit = current gross benefit × 1.036
Here are several hypothetical examples:
| Current Gross Monthly Benefit | Estimated 3.6% Increase | Estimated New Gross Benefit |
|---|---|---|
| $1,000 | $36 | $1,036 |
| $1,500 | $54 | $1,554 |
| $2,000 | $72 | $2,072 |
| $2,500 | $90 | $2,590 |
| $3,000 | $108 | $3,108 |
| $4,000 | $144 | $4,144 |
These are estimates, not promises of the exact amount SSA will calculate.
Why Your Exact Increase May Not Equal 3.6% of Your Current Check
Social Security does not simply take the amount deposited into your bank account and add 3.6%.
SSA explains that the COLA is applied through the Social Security benefit formula. The agency increases the beneficiary’s primary insurance amount, then applies applicable adjustments and rounding rules before arriving at the monthly benefit.
Because of that calculation process, your exact gross-benefit increase may differ slightly from a simple current-benefit-times-3.6% calculation.
And that is before deductions are considered.
Your Gross Benefit and Your Bank Deposit Are Not Always the Same Number
Suppose your current gross Social Security benefit is $2,000 per month.
A simple 3.6% estimate gives you:
$2,000 × 3.6% = $72
That would put the estimated new gross benefit at about $2,072 per month.
But your bank deposit may not rise by the full $72 if the deductions coming out of your Social Security benefit also change.
Medicare Part B can reduce the increase you see in your deposit
For most people who receive both Social Security and Medicare Part B, the Part B premium is automatically deducted from the monthly Social Security payment.
That means a change in the Medicare premium can affect how much of your COLA you actually see in your bank account.
As of October 19, 2026, SSA’s COLA announcement does not give beneficiaries a final individualized 2027 Medicare deduction. SSA says Medicare enrollees will be able to see their 2027 premium information in their personal Social Security notice beginning in late November.
So if Medicare comes out of your Social Security benefit, it is safer to think of your calculation this way:
Change in net payment ≈ gross COLA increase − increase in Medicare deductions − other changed deductions
Do not plug an estimated Medicare premium into your household budget and treat it as final. Wait for the official amount.
Medicare Advantage or drug-plan premiums may also be withheld
Some people elect to have Medicare Advantage or Medicare Part D plan premiums deducted from their Social Security payments.
If one of those premiums changes for 2027, your direct deposit can change even though your Social Security gross benefit received the COLA.
Federal tax withholding can affect the deposit too
If you have elected to have federal income tax withheld from your Social Security benefits, the amount withheld can also affect what reaches your bank account.
That does not reduce your official COLA. It changes the amount you receive after withholding.
SSA’s Average Increase Is About $75 a Month
The Social Security Administration estimates that the average Social Security retirement benefit will increase by about $75 per month because of the 2027 COLA.
But “average” is doing important work there.
If your benefit is lower than the average, your dollar increase will generally be lower. If your benefit is higher, your increase will generally be higher.
A percentage increase does not give everyone the same number of extra dollars.
For example, a hypothetical $1,500 monthly benefit produces an estimated $54 increase, while a hypothetical $3,000 benefit produces an estimated $108 increase.
Both received the same 3.6% adjustment.
What About SSI in 2027?
The 3.6% adjustment also applies to federal Supplemental Security Income payment levels.
For 2027, the maximum federal SSI payment standard rises to:
- $1,029 per month for an eligible individual, up from $994 in 2026.
- $1,544 per month for an eligible couple, up from $1,491 in 2026.
Those are maximum federal amounts. The amount a particular person receives can be lower because SSI payments depend on countable income and other eligibility rules, and some states provide supplemental payments.
Working While Collecting Social Security? The Earnings Limits Also Changed
If you are below full retirement age and still working, the COLA is not the only 2027 Social Security number worth checking.
For 2027, the retirement earnings-test limit rises to $25,560 per year for people who are under full retirement age for the entire year.
SSA withholds $1 in benefits for every $2 earned above that limit.
For someone reaching full retirement age during 2027, the higher earnings limit is $67,920. Before the month full retirement age is reached, SSA withholds $1 for every $3 earned over that limit.
Beginning with the month you reach full retirement age, the retirement earnings test no longer applies.
If this rule affects you, looking only at the 3.6% COLA will not tell you what your monthly payments will actually look like.
How to Find Your Exact 2027 Social Security Amount
You do not have to rely on an online COLA calculator or estimate forever.
SSA says people with personal my Social Security accounts can see their personalized COLA notices online starting in late November 2026 if they meet the agency’s account and paperless-notice requirements.
The personalized notice will show your actual new benefit amount and applicable deductions.
Beneficiaries who receive paper notices instead should receive their COLA notice by mail in December.
That notice is the number to use when updating your 2027 budget.
A Simple Way to Plan Before Your Notice Arrives
If you want a reasonable estimate now without counting money you may not actually receive, use this three-step approach:
- Find your current gross Social Security benefit. Do not start with the bank deposit if Medicare, taxes, or other amounts are being withheld.
- Multiply the gross amount by 0.036. Treat the result as an estimate of your COLA increase, not an exact SSA calculation.
- Wait for your official notice before committing the extra money. Check the new gross benefit and every listed deduction, then calculate the true change in your monthly deposit.
If you receive $2,500 gross now, for example, a reasonable planning estimate is a $90 monthly gross increase. But it would be premature to increase your spending plan by the full $90 until you know whether Medicare premiums or other deductions are changing too.
What Should You Do With the Extra Money?
A COLA is designed to help Social Security benefits keep pace with rising prices. It is not necessarily extra spending money in the same way a raise above inflation might be.
Before assigning the increase somewhere new, check whether expenses such as housing, utilities, food, insurance, prescriptions, or medical costs have already risen.
If your regular expenses have not absorbed the full increase, even a modest amount left over can have a job:
- Rebuild part of an emergency fund.
- Cover an annual bill that tends to disrupt the monthly budget.
- Pay down high-interest debt.
- Set aside money for medical copays or prescriptions.
- Keep the extra amount in savings until you know what your 2027 expenses look like.
You do not need to make that decision before the first higher payment arrives.
The Bottom Line
The 2027 Social Security COLA is 3.6%, and the Social Security Administration estimates that the average retirement benefit will rise by about $75 a month.
To estimate your own increase, multiply your current gross benefit by 0.036. That gives you a useful planning number.
But do not assume the result is exactly how much more will appear in your bank account.
SSA’s calculation and rounding rules can cause small differences, and Medicare premiums, tax withholding, plan premiums, or other deductions can change the net amount you receive.
The number that matters most for your household budget is the one on your personalized 2027 COLA notice: your new benefit minus your actual deductions.
Information verified October 19, 2026. Social Security and Medicare amounts, rules, and individual deductions can vary by beneficiary. Use your official Social Security notice for your final 2027 benefit amount.